
Case Study: Restructuring Commercial Property Finance to Improve Borrowing Capacity for Self-Employed Business Owners in Airlie Beach.
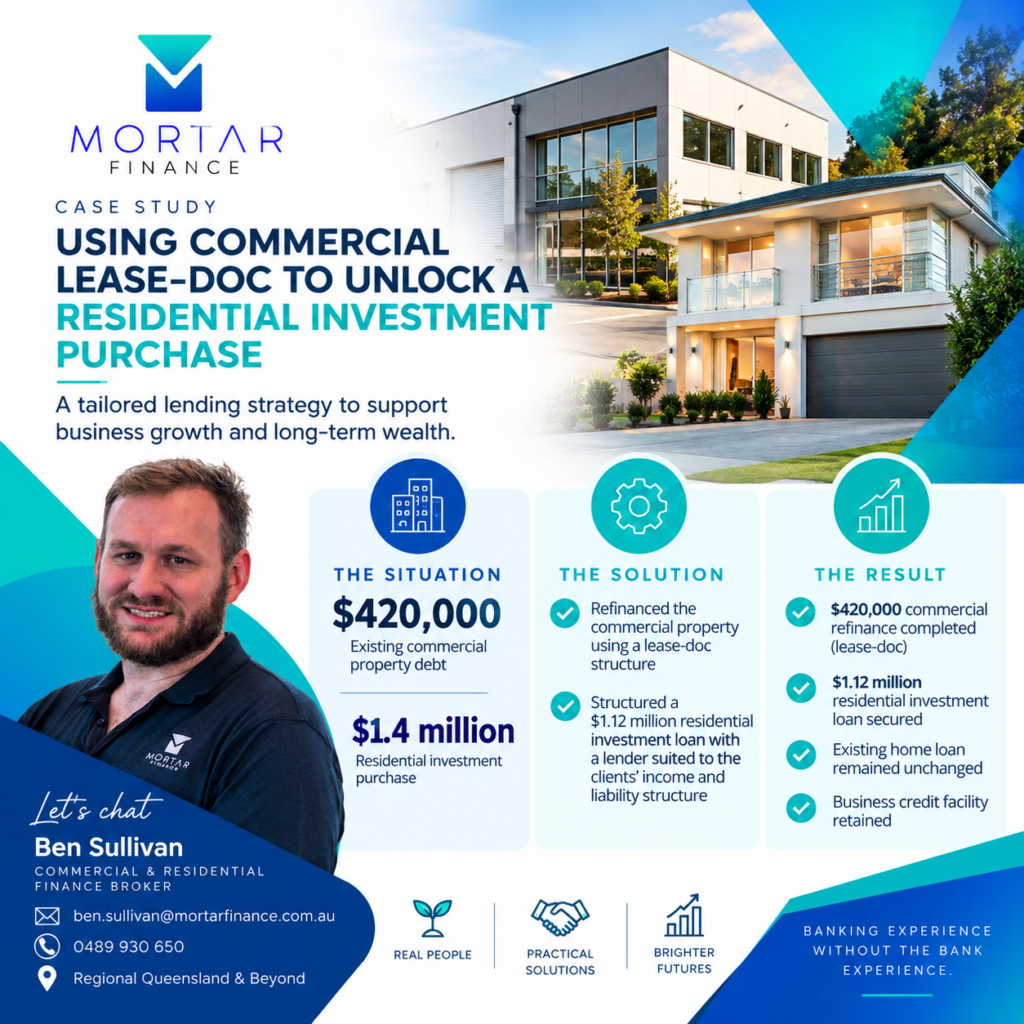
Mortar Finance recently assisted established business owners in Airlie Beach, Queensland to restructure approximately $420,000 in commercial property debt before proceeding with the purchase of a $1.4 million residential investment property.
The clients already held their principal residence, commercial property and facilities associated with their business. Their objective was to expand their residential investment portfolio without unnecessarily refinancing their existing home loan or closing valuable business facilities.
The solution required more than simply finding a lender for the new investment property.
By first restructuring the commercial property debt using a lease-doc commercial lending strategy, Mortar Finance was able to appropriately separate the commercial property lending from the clients’ broader personal lending position.
We could then assess the residential investment purchase across lenders whose policies were better suited to the clients’ combination of self-employed income, PAYG earnings and company liabilities.
The result was a $420,000 commercial property refinance, followed by $1.12 million in new residential investment lending to complete the $1.4 million purchase.
The clients were established business owners in Airlie Beach looking to purchase a $1.4 million residential investment property as part of their longer-term wealth creation strategy.
Their financial position was more complex than a standard residential investment application.
They already held their principal residence, a commercial property and facilities associated with the operation of their business. Their income was also derived from a combination of self-employed/director income and PAYG employment income.
Importantly, the clients did not want to achieve the new purchase by unnecessarily disrupting lending arrangements that were already working for them.
Their objective was to complete the $1.4 million investment purchase while leaving their existing owner-occupied home loan unchanged and retaining the business facilities required for their ongoing operations.
Achieving this required us to look at the clients’ overall lending structure, rather than assessing the proposed residential investment loan in isolation.
The clients had approximately $420,000 in existing commercial property debt, which had implications for their overall borrowing capacity when assessed alongside the proposed residential investment lending.
Under a conventional servicing approach, the clients’ commercial debt, company liabilities, personal commitments and proposed residential lending could all influence the overall servicing assessment.
There were also material differences between lenders in how they assessed the clients’ income and liabilities.
One applicant’s PAYG income had recently increased. While some lenders would restrict their assessment to the lower historical financial-year earnings, others could recognise the higher current income evidenced by recent payslips.
Treatment of the clients’ company liabilities also varied between lenders.
The challenge was therefore not simply finding the lowest residential investment rate.
We first needed to determine whether the existing commercial property debt could be structured differently and then identify a residential lender whose credit policy appropriately recognised the clients’ current income and liability position.
Mortar Finance reviewed the clients’ existing commercial property and identified an opportunity to refinance approximately $420,000 using a lease-doc commercial lending structure.
The commercial property generated approximately $45,000 per annum in base rental income, plus outgoings.
Rather than relying solely on a conventional global servicing assessment incorporating the clients’ broader personal and business position, the proposed lease-doc structure allowed the lender to place greater emphasis on the rental income generated by the commercial property itself.
The refinance was structured at approximately 65% loan-to-value ratio (LVR).
At the proposed lending terms, the commercial property produced an Interest Cover Ratio (ICR) of approximately 1.52x, satisfying the lender’s minimum requirement of 1.50x.
This provided an appropriate pathway to refinance the approximately $420,000 commercial property debt using a lending methodology suited to the income-producing asset.
With the commercial property position addressed, we could then move to the second stage of the strategy.
Mortar Finance then modelled the proposed $1.4 million residential investment purchase across multiple residential lenders.
Lender selection was particularly important because policies varied considerably in their treatment of self-employed income, current PAYG earnings and company liabilities.
The selected lender was able to recognise one applicant’s higher current PAYG earnings using recent payslips, rather than limiting the servicing assessment to the lower historical financial-year income.
The lender also provided more suitable treatment of the relevant company liabilities.
Together with the commercial refinance strategy, this enabled the clients to secure the required $1.12 million residential investment loan to complete their $1.4 million property purchase.
Importantly, their existing owner-occupied home loan remained unchanged.
The clients were also able to retain an existing business credit facility that another lender would have required them to close as part of the residential application.
The strategy resulted in two separate lending transactions working together towards one broader objective.
The clients achieved:
Most importantly, the clients were able to progress with their investment strategy without unnecessarily restructuring their home lending or sacrificing business facilities they wanted to retain.
For self-employed business owners, borrowing capacity is not always determined simply by how much income they or their business generate.
The way existing debt is structured, how individual lenders treat company liabilities, the income used for servicing and the lending methodology applied to different assets can all influence the outcome.
In this case, looking only at the proposed residential investment purchase would have missed an important part of the solution.
By reviewing the clients’ commercial property position first, Mortar Finance was able to establish a lending structure suited to the income-producing commercial asset before separately assessing the residential investment purchase.
The result demonstrates why commercial and residential lending strategies sometimes need to work together, particularly for self-employed clients with more complex income, asset and liability structures.
If you are a business owner in Airlie Beach, the Whitsundays or broader Queensland looking to purchase an investment property, refinance commercial property or review how your existing business and personal lending is structured, Mortar Finance can assess the broader position and help determine an appropriate funding strategy.
Project Details
Meet your financial tailors – measuring your unique needs and designing custom money solutions that fit you perfectly.
No one-size-fits-all here; we’re all about making your finances as individual as you are.
We’re passionate about helping our clients achieve financial success. See what they have to say about our expertise.
This was our first time buying a commercial property and the knowledge, professionalism and service we received was nothing short of amazing. We will be using the team again for any of our future needs and would recommend him to anyone in need of assistance.
5 stars doesn't explain the awesome experience of having your finance organized while you continue to manage business operations. No bank bully, only a smooth transition with no wasted time. Strongly recommend this professional service.
You know when you have a question but think it's silly or worse stupid, so you don't worry about asking it? Well, that'll never happen with these guys. They welcomed all our questions and made sure we understood it even if it meant by going through it again and again. Very patient, lovely, flexible and most importantly they know what they're doing. Made our loan application such a breeze. I can't thank these guys enough. From the first call to the settlement date, they were always in our corner trying to get the best deal for us. 100% use them again and would recommend them without any hesitation.
Nick assisted us in purchasing a new company vehicle during EOFY. This was an urgent transaction and I'm not sure we would have been successful without Nick's help and expertise. He did all the background work, talked us through any paperwork we had to complete, and made the whole process seamless. We will definitely be using Nick and the Mortar Finance team for future finance needs.
I’ve been fortunate enough to have dealt with Mortar Finance for over 3 years and they’ve been SO helpful. I purchased my first home back in 2020 by myself and since then, I’ve received ongoing support from the team. The team are not only knowledgeable but incredibly supportive and have open lines of communication throughout the whole journey. It can be a very daunting process but I would happily recommend them to anyone I know.
Highly recommended – Zac and the team at Mortar Finance made it seamless and smooth from start to finish. I have a complicated structure being self employed – Mortar were able to break down our structure and present it in a certain way to the bank in order for our loan needs to be met.
What an amazing and supportive business from the beginning. I could not fault the service, communication and adaptability. I would use again and recommend with confidence. My son recommended them to me, my daughter than used them and then me. No once off. Consistently do a great job.